How Data Analytics is Transforming Debt Recovery and Risk Management
For decades, debt recovery ran on a simple logic: call every account, in roughly the order it landed on a desk, and work through the list. That model made sense when portfolios were small and delinquency patterns were easy to read by instinct. It breaks down fast at scale. A lender with hundreds of thousands of overdue accounts cannot afford to treat a borrower who missed one payment due to a timing issue the same way it treats an account with a six-month pattern of default risk.
This is the gap predictive analytics is closing — and it’s reshaping how debt recovery and collections operate at every level, from the call floor to the boardroom.
From Reactive Calling to Predictive Prioritization
Traditional collection queues are largely reactive: aging buckets (30/60/90 days past due) determine who gets contacted and when. Predictive analytics changes the starting question from “how overdue is this account?” to “how likely is this account to be recovered, and what will it take?”
Modern collection platforms build models on variables such as:
- Payment history patterns — not just whether a payment was missed, but the trajectory leading up to it
- Behavioral signals — response rates to prior outreach, channel preference, time-of-day engagement
- Macroeconomic and contextual data — employment sector trends, seasonal cash-flow cycles, regional economic indicators
- Account-level risk scores — a composite likelihood-to-pay metric refreshed as new data arrives
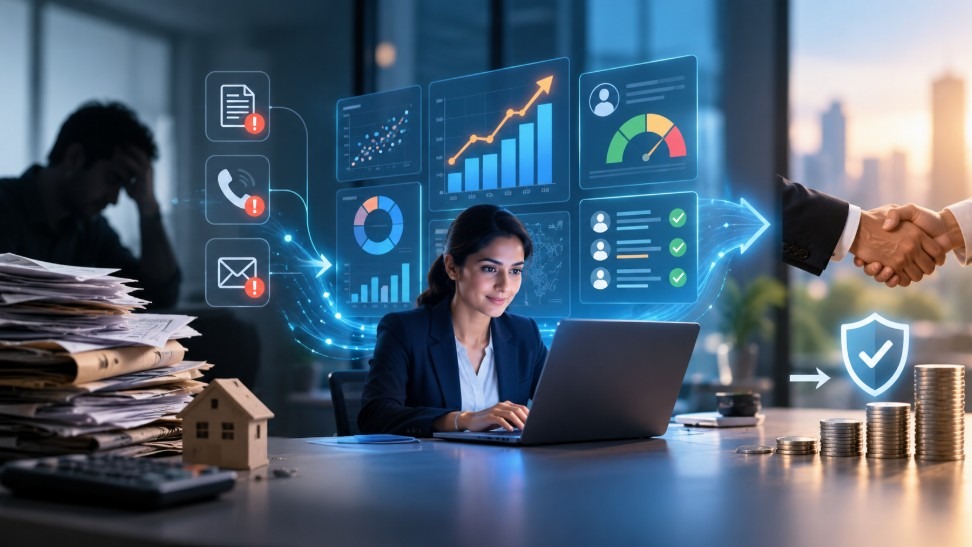
These models don’t just rank accounts by dollar value or days overdue. They estimate the probability of recovery under different strategies, allowing collection teams to route each account to the right treatment — a gentle reminder, a structured repayment offer, or escalation — before a single dialer minute is spent.
Optimizing Resource Allocation, Not Just Contact Volume
The operational impact of this shift is significant. Collection teams are a finite resource: agent hours, outbound call capacity, and legal escalation bandwidth are all constrained. Predictive queue management reallocates that capacity toward the accounts where effort actually moves the needle.
In practice, this looks like:
- Tiered effort models — high-probability, high-value accounts get proactive, personalized outreach; low-probability accounts are shifted to automated or low-touch channels, preserving agent time for cases where it matters most
- Dynamic re-scoring — as new payment or contact data comes in, accounts move between tiers in near real time rather than sitting in a static bucket for 30 days
- Channel optimization — data on past response rates determines whether an SMS nudge, an email, or a live call is most likely to convert for a given segment
The result is fewer wasted contact attempts, lower cost-to-collect, and — counterintuitively — often a better borrower experience, since outreach becomes more relevant and less repetitive.
Risk Management Benefits Beyond the Collections Floor
The same data infrastructure that powers collection queues generates value further upstream. Portfolio-level analytics allow risk and governance teams to:
- Identify emerging default clusters early — spotting concentration risk in a geography, product line, or borrower segment before it becomes a portfolio-wide problem
- Stress-test recovery assumptions — modeling how recovery rates might shift under changed economic conditions, which feeds directly into provisioning and capital adequacy decisions
- Improve regulatory and audit readiness — a data-driven, documented prioritization logic is easier to defend to regulators and auditors than “we called accounts in the order they came in”
For boards and governance committees, this matters because debt recovery performance is no longer just an operational metric buried in a collections report — it’s a forward-looking input to credit risk strategy.
Financial Literacy as a Byproduct of Better Data
There’s a less obvious benefit worth highlighting for stakeholders focused on financial inclusion: predictive analytics, done responsibly, tends to produce more tailored — not more aggressive — borrower communication. When a model can distinguish between a borrower facing genuine hardship and one who is simply disorganized, the resulting outreach can be structured accordingly: hardship support and restructuring options for one, straightforward reminders for the other.
This segmentation supports broader financial literacy goals by ensuring communication is relevant rather than generic, and by creating natural touchpoints for education around repayment planning, rather than blanket pressure tactics.
What This Means for Scaling Operations
For lenders and recovery partners looking to scale, the operational case for analytics-driven collections is straightforward:
- Lower cost-to-collect through better-targeted effort
- Higher recovery rates by matching strategy to borrower likelihood-to-pay
- Scalable infrastructure that doesn’t require proportional headcount growth as portfolios expand
- Better compliance posture through documented, consistent, data-backed decisioning
This is precisely where BundlePe’s approach is oriented — using data-driven prioritization to help collection operations scale efficiently without compromising recovery quality or borrower treatment standards.