The Recovery Roadmap: Navigating Delinquencies in India’s Lending Ecosystem
A young professional in Pune takes a personal loan for a wedding. A trader in Surat borrows to restock before Diwali. Sooner or later, someone in that mix misses a payment.
That’s the flip side of India’s credit boom. More people can access loans than ever before — which is great, until repayments stop coming on time. What happens next says a lot about how healthy a lender’s business really is.
Why Delinquencies Keep Rising
Ask anyone in banking or NBFC circles, and they’ll tell you overdue accounts are climbing across personal loans, credit cards, and small business credit. A few reasons stand out:
- Financial literacy hasn’t kept pace with credit access. Many first-time borrowers don’t fully understand EMIs or interest.
- Income isn’t always steady. Gig workers and small traders often have unpredictable cash flow.
- Over-borrowing is easy. Instant credit apps make it simple to take on more loans than one can manage.
- Life gets in the way. Medical bills, job loss, and family emergencies don’t wait for due dates.
Importantly, a missed EMI usually isn’t fraud — it’s often a temporary crunch or a communication gap. That distinction should shape how recovery is handled.
Why the Old Recovery Playbook Is Failing
For years, recovery meant aggressive calls and repeated visits, treating every defaulter like a runaway borrower. That approach is breaking down fast:
- RBI rules are stricter on agent conduct, call timings, and borrower treatment.
- Borrowers know their rights — one bad experience can spiral on social media.
- It’s inefficient, treating every case the same regardless of the reason behind the delay.
Recovery isn’t just a back-office task anymore. It’s one of the most sensitive touchpoints a lender has with a customer.
What Smarter Recovery Looks Like Today
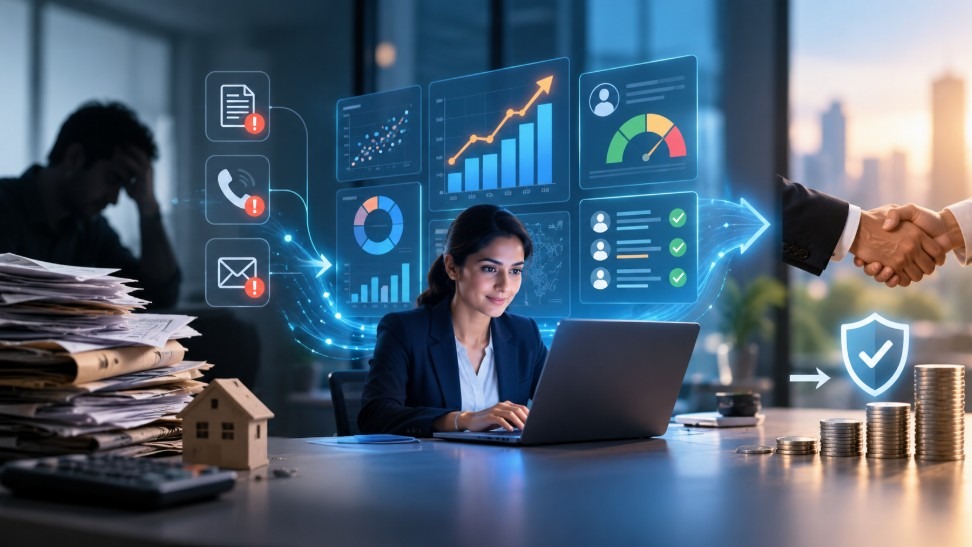
- Segment borrowers. A five-day delay after years of clean payments isn’t the same as three months of silence — treat them differently.
- Predict, don’t just react. Data signals like spending changes or delayed salaries can flag risk before a payment is even missed.
- Communicate like a human. Multilingual, respectful outreach across calls, SMS, and WhatsApp works better than threats.
- Offer real solutions. Restructured EMIs or settlement options bring borrowers back far more often than ultimatums.
- Stay compliant, always. Every call and message should sit within RBI fair-practice guidelines — non-negotiable.
- Use tech to scale empathy. Automation handles routine reminders, freeing agents for the conversations that need real judgment.
Recovery Is Relationship Management, Not Just Collections
A borrower helped through a rough patch often stays loyal and returns for future credit. One who’s hounded is a customer — and their network — lost for good, plus a possible compliance headache.
That’s why more lenders now lean on specialized recovery partners: structured processes, trained agents, and compliant, tech-backed workflows that a stretched in-house team simply can’t match.
Where This Is Headed
India’s credit market will only keep growing — more borrowers, more first-timers, more small businesses. The lenders who win won’t be the ones collecting the hardest. They’ll be the ones recovering smartly: structured, data-driven, and genuinely respectful.
Because good recovery isn’t just about getting money back — it’s about keeping the whole lending ecosystem trustworthy and built to last.